
 Omanghana
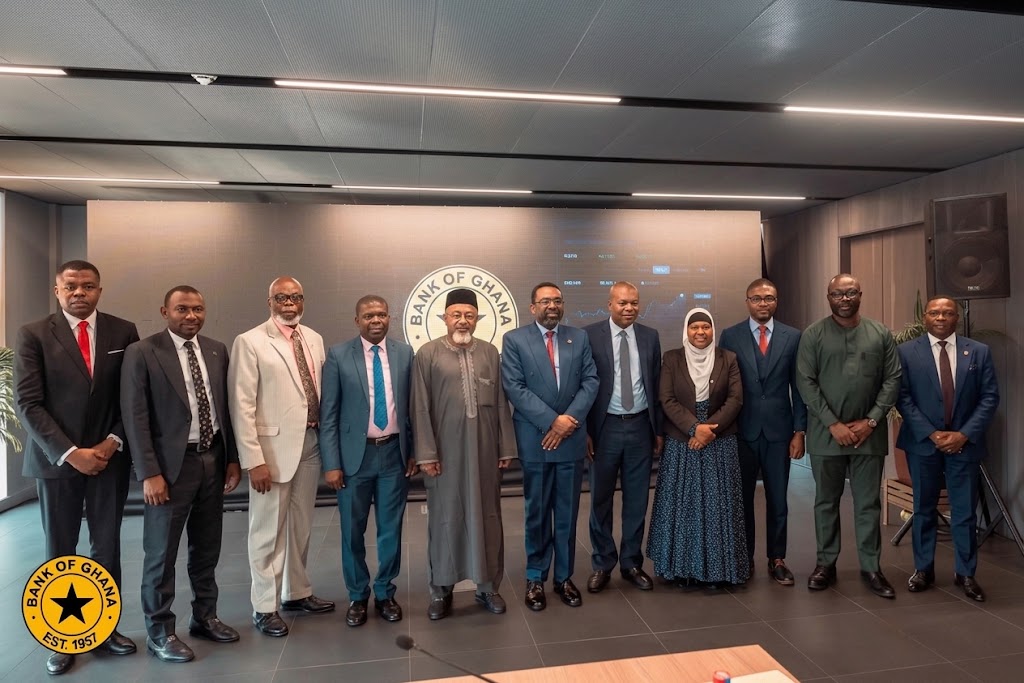
The Bank of Ghana’s appointment of Nigerian Islamic finance specialist Professor Bashir Aliyu Umar to lead its Non-Interest Financial Advisory Council has generated debate within Ghana’s financial sector.
The discussion centers on whether the country should rely on regional expertise or place greater emphasis on domestic professionals as it prepares to implement non-interest banking.
Contrary to claims that the Bank engaged a single foreign consultant to design the system, the central bank has inaugurated a five-member council to advise it on the governance, regulation and supervision of non-interest financial institutions.
The council is expected to support the transition from developing a regulatory framework to implementing non-interest banking as a distinct segment of Ghana’s financial industry.
Professor Umar is affiliated with Bayero University in Kano and serves as Deputy Chairman of the Financial Regulation Advisory Council of Experts at the Central Bank of Nigeria.
He previously advised the Nigerian central bank on non-interest banking between 2010 and 2014, when the country was developing its regulatory system and licensing its first institutions in the sector.
Supporters of the appointment argue that Nigeria offers relevant practical experience because it already has established non-interest banks, including Jaiz Bank and Lotus Bank. Its experience could help Ghana anticipate regulatory and operational difficulties.
Critics, however, have questioned why Ghanaian legal, banking and financial experts were not given greater prominence in leading the process. They argue that domestic professionals are better positioned to understand Ghana’s taxation system, banking laws and market conditions.
Financial sector observers have stressed that international models cannot simply be transferred to Ghana without careful adaptation.
Issues requiring local regulatory attention include profit-and-loss sharing arrangements, asset-backed financing, Sukuk instruments, liquidity management and statutory reserve requirements.
The central bank must also determine how non-interest institutions will interact with Ghana’s existing taxation and deposit-protection systems without creating unintended disadvantages or preferential treatment.
Non-interest banking prohibits the payment or receipt of interest and generally relies on ethical, asset-backed and risk-sharing financial arrangements. Although commonly associated with Islamic finance, the Bank of Ghana has emphasized that the services will be open to people of all religious backgrounds.
Advocates believe the system could improve financial inclusion by attracting individuals and businesses that avoid conventional banking for religious or ethical reasons.
It could also provide alternative financing for small and medium-sized enterprises that struggle to meet collateral requirements under traditional loan arrangements.
Regulatory governance remains another major area of interest. Stakeholders are awaiting details on the establishment of institutional advisory boards, product-approval procedures and consumer-protection safeguards.
Licensed banks may be permitted to operate dedicated non-interest windows, while other institutions could apply to operate as standalone non-interest banks under the central bank’s supervision.
The Bank of Ghana published a draft framework in December 2025 and issued operational guidelines in January 2026. At least one indigenous bank has reportedly applied for a license, while several others are preparing applications.
The central bank hopes to issue Ghana’s first non-interest banking license before the end of 2026.
Source: Omanghana